Medicare AEP: What To Know and Deadlines
Medicare’s Annual Enrollment Period is an important opportunity to revisit the health coverage you rely on. It can be tempting to let an existing plan renew automatically, especially if it has...
Read more
Diabetes Awareness Month - November - How Benefits Can Support
Diabetes is one of the most widespread chronic health conditions in the United States, affecting millions of people and families. The CDC’s latest National Diabetes Statistics Report estimates that...
Read more
ACA Open Enrollment Period Begins Soon - Federal Marketplace
ACA Marketplace open enrollment for 2027 health coverage is approaching, and an early review can make the process far easier to manage. Whether you will be choosing Marketplace insurance for the...
Read more
Employee Financial Wellness Benefits That Build Security
Financial pressure affects employees at every income level. Day-to-day expenses, debt, and unplanned costs can make it difficult to feel financially secure, even with reliable employment. Those...
Read more
How to Prepare for Marketplace Open Enrollment
Marketplace Open Enrollment is an important opportunity to enroll in health coverage, update an existing plan, or compare alternatives for the year ahead. Preparing before enrollment opens can make...
Read more
Medicare AEP Planning Tips for Coastal Georgia Clients
Medicare’s Annual Enrollment Period (AEP) is easier to manage when you begin preparing before the deadline approaches. From October 15 through December 7 each year, Medicare beneficiaries can...
Read more
UV Safety Awareness Month - July - Skin Cancer Prevention
UV exposure affects your skin every day, not just during time spent outdoors. Even routine moments—like driving, walking the dog, or sitting near a sunny window—can slowly contribute to long-term...
Read more
Medicare and Eye Care: What’s Covered and What Isn’t
Maintaining healthy vision becomes increasingly important with age, especially for older adults who rely on consistent eye care to support daily life and overall wellness. June 6th, observed as...
Read more
Pre-Summer Preventive Care Reminder
As the warmer months approach, many people in coastal Georgia begin filling their calendars with vacations, family events, and outdoor activities. These busy schedules often push routine health...
Read more
Understanding Your Medicare Advantage Trial Right
Choosing Medicare coverage can feel complicated, especially with the many plans, rules, and enrollment paths to sort through. One area that often gets overlooked is the Medicare Advantage trial...
Read more
Small Group Benefits: Affordable Solutions for Small Teams
A Small Team Faces Big DecisionsImagine you're a small business owner wearing multiple hats—managing daily operations, handling customer service, and worrying about your budget. Among these...
Read more
End-of-Year Life Checkup: Is Your Coverage Still Right?
As the year comes to a close, it's a natural time for reflection. The holiday season and open enrollment create the perfect backdrop for considering whether your life insurance coverage is still...
Read more
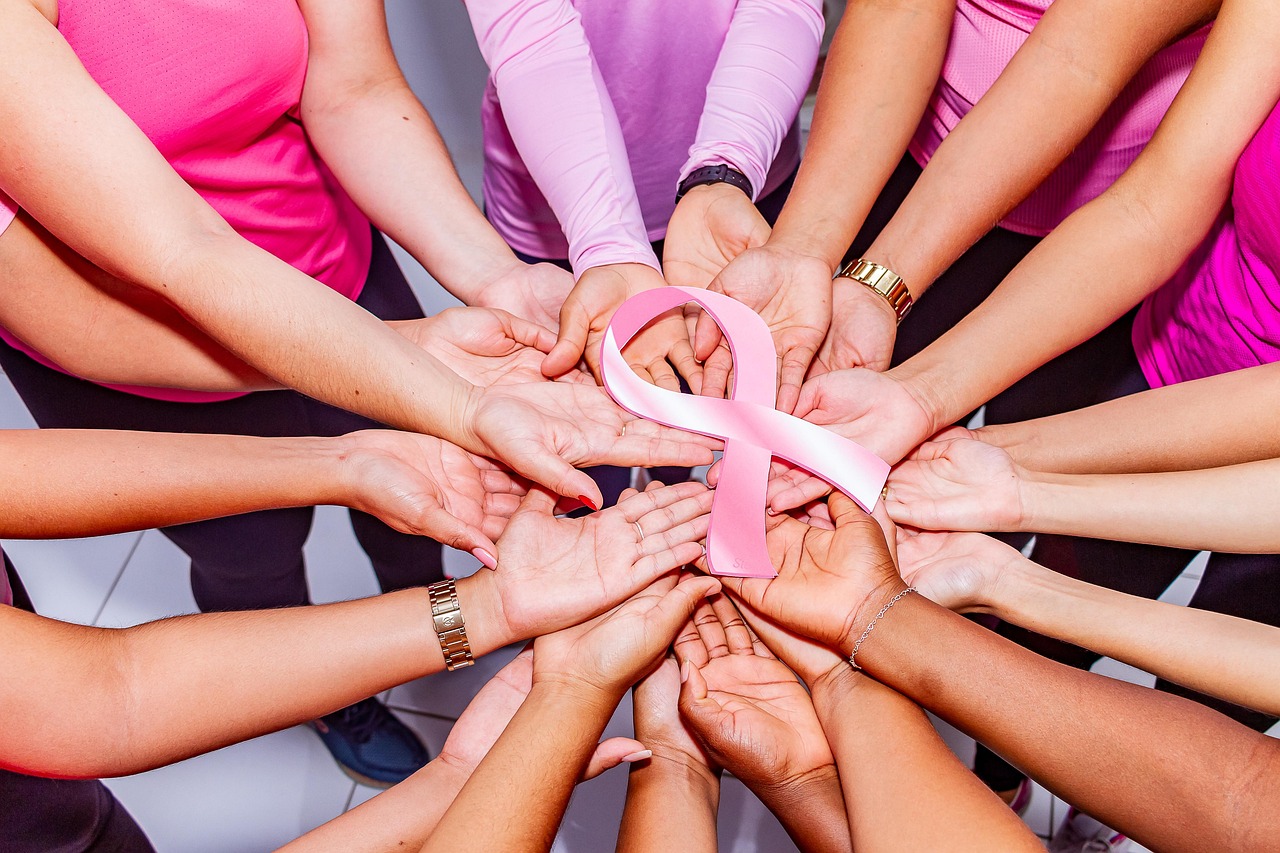
Breast Cancer Awareness: Your Role in Saving Lives
A Month of Awareness and Action October marks Breast Cancer Awareness Month—a time to honor those touched by this pervasive illness, to educate ourselves and others, and to affirm that...
Read more
Preparing for Medicare Open Enrollment
Empower Your Medicare JourneyThe Medicare Open Enrollment period from October 15 to December 7 can be an empowering time to enhance your healthcare plan. It doesn't have to be stressful—think of it...
Read more
Life Insurance: A Key to Financial Security & Wellness
Life Insurance Awareness Month: A Time to ReflectSeptember is here, marking Life Insurance Awareness Month—a perfect opportunity to reassess your financial plans. We understand that life insurance...
Read more
Plan Ahead: Use Benefits Before 2026
As the End of the Year Approaches, Don’t Overlook BenefitsThe end of the year can creep up on us faster than expected. Amid holiday preparations and celebrations, it’s easy to overlook the benefits...
Read more
Medicare Annual Enrollment Period: 5 Key FAQs
Medicare’s Annual Enrollment Period: A Crucial WindowEvery year, from October 15 to December 7, Medicare’s Annual Enrollment Period (AEP) offers a limited-time opportunity to make changes to your...
Read more
Disability Income Protection: Your Financial Safeguard
Understanding Disability Income ProtectionDisability income insurance is a crucial financial safety net, providing income replacement benefits if you become unable to work due to illness or injury....
Read more
View more